The reel spins, the boat rocks, and your bankroll starts moving
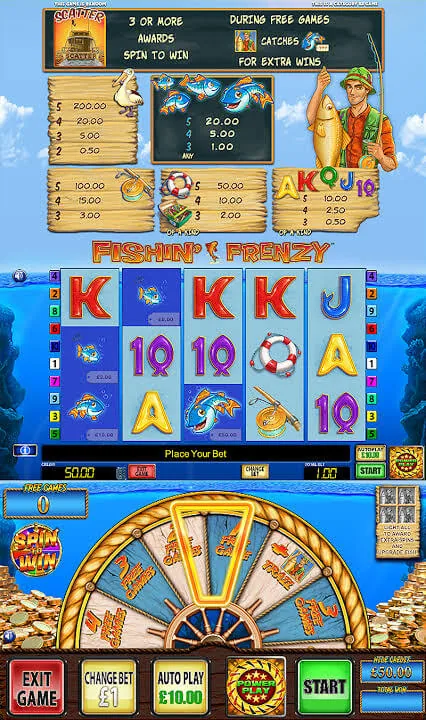
A blue reel fills the screen, a small boat bobs at the side and the symbols line up with the soft plop of a fishing float. That is the first impression of Fishin Frenzy on a phone: colourful, quick and easy to understand. The less obvious part begins when the balance changes from a harmless demonstration balance to real money.
Before downloading anything, it is worth separating the game from the route used to reach it. Fishin Frenzy may appear inside an app, a mobile browser or an add-to-home-screen shortcut, while the operator supplying the game controls deposits, withdrawals, verification and account support. This guide explains what the app listing can tell you, where installation can go wrong and how to judge whether the product in front of you is legitimate.
The store listing at a glance
The figures below form a plausible, internally consistent store-style card for Fishin Frenzy. They are illustrative market examples rather than a verified promise about the live listing in the UK App Store. An operator may distribute its own build with a different size, version number and set of features.
What appears on the five small screens
The opening screen is deliberately simple. A reel-filled grid sits in the centre of a blue underwater scene, with the stake and total win displayed around it. Buttons for the paytable, sound, settings and the main spin control are large enough for a thumb, but the important information is not buried beneath decorative fishing imagery.
- The home screen shows the Fishin Frenzy logo, a prominent Play button, the current account balance and a small route into the cashier. If the product is an operator’s app, this screen may also contain responsible-gambling controls and account verification prompts.
- The reel screen gives the game its main rhythm. The player sets a stake, starts a spin and watches symbols settle across the reels. Fishing-related symbols such as a fish, tackle box and fishing rod form the paying combinations, while special symbols can change the sequence and produce a multiplier rather than a guaranteed cash prize.
- The paytable explains every paying symbol, the reel layout, the conditions attached to bonus features and the rules used to calculate wins. It should be read before treating a large animated symbol as an automatic payout.
- The cashier lists deposits, withdrawals, payment methods and any verification status. A UK-facing product should show amounts in pounds, including balances such as £10.00, rather than converting them into an unfamiliar currency or obscuring the stake in the background.
- The settings screen normally contains sound, animation and data-saving options. It may also provide access to responsible-gambling tools, including deposit limits, session reminders, reality checks and links to GAMSTOP.
The app does more than reproduce the reels. It stores preferences, loads game assets, manages the session with the operator and provides the cashier and verification journey. Those extra functions explain why an app download can be larger than the base game and why a browser shortcut may be more convenient for an occasional player.
Four ways to reach Fishin Frenzy, with a different risk attached
The safest route is the one provided by a UKGC-licensed operator. The app, browser and shortcut can all be legitimate, but they are not interchangeable. Check the operator in the UKGC public register and match the licence number shown in the site footer before depositing.
- Mobile browser: open the operator’s official site, locate Fishin Frenzy and choose its browser play option. The main risk is mistaking an advertisement for the operator’s own address, so type or select the verified destination carefully. The game may be easier to abandon when a fixed deposit limit or session reminder is reached.
- Add to Home Screen: in Safari, open the game and use the share or menu option to add it to the home screen. This creates a shortcut rather than a full native app. Its risk is visual confusion: the icon may look official while leading back to the same site, so confirm that the destination still uses HTTPS and the expected operator footer.
- Operator app: look for the operator’s own App Store listing or use its official in-app installation prompt. This route usually offers better cashier, verification and support integration. The risk is installing the wrong publisher’s app or an outdated build, so check the developer name and permissions before signing in.
- APK route: some operators distribute an Android package outside Google Play. An APK is an executable installation file, which makes sideloading materially riskier. Do not install one merely because it promises free spins or a larger bonus; unknown packages may contain intrusive permissions, unwanted software or altered payment behaviour.
What your phone must handle, and what the game may ask for
Fishin Frenzy is designed for modern phones rather than specialist hardware. A practical baseline is iOS 15 or later, or Android 10 or later, with at least 2 GB of free storage. Allow more space for the app, cached graphics and operating-system updates. A recent mid-range handset with a stable mobile connection is generally more important than a high specification.
- Network access is required for the account, game rounds, deposits and withdrawals. A poor connection can make a spin appear delayed; the operator’s server should remain the record of the result rather than the animation alone.
- Storage access may be requested for installation files, screenshots or cached assets. Broad access to all photographs is disproportionate for a fishing game and deserves investigation.
- Camera access is sometimes used for identity-document checks, but it should be requested only during the relevant verification stage. A game should not require it merely to start the reels.
- Notifications can support account alerts and responsible-gambling reminders. Marketing notifications are optional and may be disabled.
- Bluetooth, precise location, contacts and microphone permissions are not needed to play the reels. Their appearance in a gambling clone is a red flag, although permissions can also be bundled by a wider operator app.
Performance settings matter on mobile data. Full-screen animation may initially load more data, while reduced animation can save battery. A locked connection is sensible for banking, but a VPN should not be used to bypass an operator’s location or legal restrictions. If payments appear in a currency other than GBP, stop and check the cashier before proceeding.
Where the money goes after the download
The download itself may cost nothing, but real-money play creates three unavoidable costs: the wager, the tax on turnover charged by the operator and the financial effect of losing sessions. Player winnings are tax-free in the UK; operators pay Remote Gaming Duty, which rises to 40% in April 2026. That does not make the game profitable, because returns are still determined by the game maths and the volatility of the reels.
- Stake caps must be enforced: £5 per spin for most adult players and £2 for players aged 18–24. A limit is a ceiling, not a target, and repeated small stakes can still create a substantial session cost.
- Operators must offer deposit limits, and affordability checks may begin once cumulative net deposits reach £150 in a month. The initial stage can use credit-reference data, with additional checks where appropriate. A limit should be set before the first spin, not after a loss.
- Common deposit examples in the UK include debit cards using Visa or Mastercard, PayPal, Apple Pay, Open Banking or Trustly, and paysafecard. Credit cards have been banned for gambling since 2020, and the payment method must be in the player’s own name.
- The first withdrawal is commonly the slowest because age and identity checks must be completed before funds leave the account. Allow roughly 24–48 hours for document review. Later withdrawals may arrive within a few hours to 24 hours through an e-wallet, the same day to two working days via Faster Payments to a bank, or one to three working days to a debit card.
- Wagering conditions, if attached to a promotional offer, can consume deposits and winnings before cash becomes withdrawable. Always read the requirement, eligible games and expiry period before treating a bonus as cash.
There is no dependable way to beat the random number generator, and no chart converts a losing run into a promised win. The practical control is to decide the maximum loss and time before opening the cashier. A stake of £1.00 with 100 spins can already risk £100.00; the displayed balance should be treated as money intended for entertainment, not another attempt to recover an earlier loss.
| Stage | What to check | Why it matters | |
|---|---|---|---|
| Before registration | UKGC register, footer licence number, 18+ notice and safer-gambling information | Confirms who is legally offering the service | → |
| Before depositing | Deposit limit, payment name, currency and affordability prompts | Keeps the intended budget visible | → |
| Before accepting an offer | Wagering, maximum conversion, expiry and eligible-game rules | Prevents a bonus from appearing more valuable than it is | → |
| Before withdrawing | Verification status, document requirements and payment destination | Reduces delays and mismatched-account problems | → |
How to expose a clone before it reaches your balance
A fake clone often copies the artwork, promises a large bonus and asks for an installation before explaining who supplies the game. The most useful defence is not a visual inspection but a licence check. Search the operator in the UKGC public register, compare its legal name and domain with the footer licence number, and confirm that the same operator appears in the app’s publisher information.
- Unexpected permissions are a warning sign. Demanding contacts, microphone, SMS, accessibility or full photo-library access for a simple slot is not justified. Review each permission and decline the optional ones.
- No recognisable cashier is a warning sign. A clone may collect a card number in an ordinary web form without giving a regulated withdrawal process, transaction history or support route.
- Pressure is a warning sign. Countdown timers, private bonus links, requests to add the page to the home screen through an unusual profile, or messages claiming that a deposit must be made immediately are common signs of fraud.
- Mismatched branding is a warning sign. The game developer, casino operator and app publisher may be different entities, but their names should be traceable rather than replaced with a generic offshore developer.
- Unverifiable clone claims are a warning sign. Testimonials, certificate badges and statements that the game is independently audited mean little unless the operator can be identified in the UKGC register.
GAMSTOP should be available as a self-exclusion route. One registration blocks access across UKGC-licensed sites for a period from six months to five years. BeGambleAware can also provide independent help. Gambling is for adults aged 18 and over; anyone affected by harmful gambling should use deposit limits, reality checks and support services rather than trying to outlast a losing run.
FAQ
Is the Fishin Frenzy app free to download and genuinely free to play?
The download can be free, and demo play may be available, but real-money play is not free. Some UKGC sites show free play only to logged-in, age-verified accounts. The important distinction is whether a demo balance is clearly separated from withdrawable cash and whether the operator’s licence can be verified.
Can I install Fishin Frenzy as an APK on an Android phone?
Only from a legitimate operator or an official app distribution route. An APK obtained from an advert, forum or unknown message can contain unwanted software and may impersonate the real game. On the iPhone, use the App Store or the operator’s official add-to-home-screen option instead of attempting an APK installation.
Why is my first withdrawal taking so long?
The first withdrawal commonly requires age and identity checks, with documents needed before funds can leave the account. A normal review can take 24–48 hours. Later withdrawals may be faster depending on the method: e-wallets usually take a few hours to 24 hours, Faster Payments to a bank the same day to two working days, and a debit card one to three working days.